Getting burial insurance with pre-existing conditions takes more homework than buying a policy at 45 with a clean chart, but it is rarely out of reach. People with diabetes, high blood pressure, a past heart attack or controlled COPD often qualify for something. What changes is the version they qualify for: full coverage from day one, coverage that phases in over two years, or a guaranteed-acceptance policy that never asks about health. We’ll show you how to tell them apart, what they cost, and where buyers get burned.
Will an Insurer Actually Approve You?
Start with simplified issue coverage. It asks a short set of yes/no health questions, and if you pass, the full benefit applies from day one. If you’re declined, guaranteed acceptance coverage takes nearly everyone in its age range (typically 50 to 85, sometimes 45), but a natural-cause death in the first two years usually returns only premiums plus about 10% interest.
- Coverage size: guaranteed policies commonly cap near $25,000; simplified issue limits run higher at some insurers.
- Funeral benchmark: NFDA’s 2023 medians were $8,300 for burial with a viewing and $6,280 for cremation with a viewing, before cemetery charges.
- Sample price (estimate): roughly $24 to $135 a month for $10,000 of simplified issue coverage, depending on age and sex.
- Waiting period: two years is standard on guaranteed policies, three at some insurers. Accidental death is generally paid in full from the start.
How Burial Insurance Works and the 3 Types of Policies
Burial insurance, sold interchangeably as final expense insurance, is a small whole life policy meant to cover a funeral, cemetery costs and a few leftover bills. Face amounts typically run from about $2,000 to $50,000, depending on the insurer. The beneficiary gets cash and can spend it as the family needs; nothing forces it toward the funeral home.
Premiums generally stay level for life, which is the trade for paying more per dollar of coverage than term life costs.
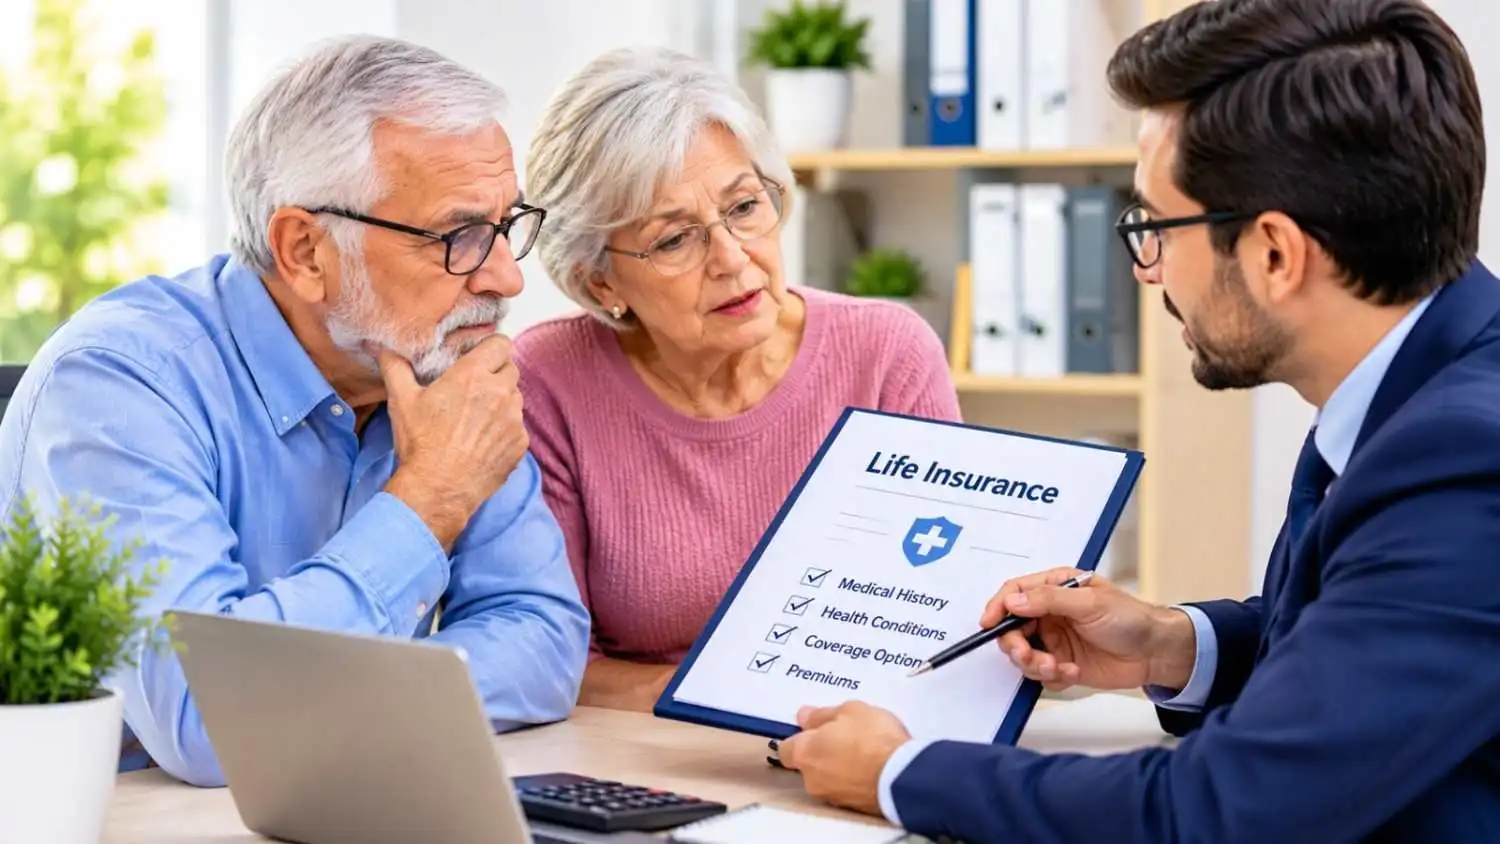
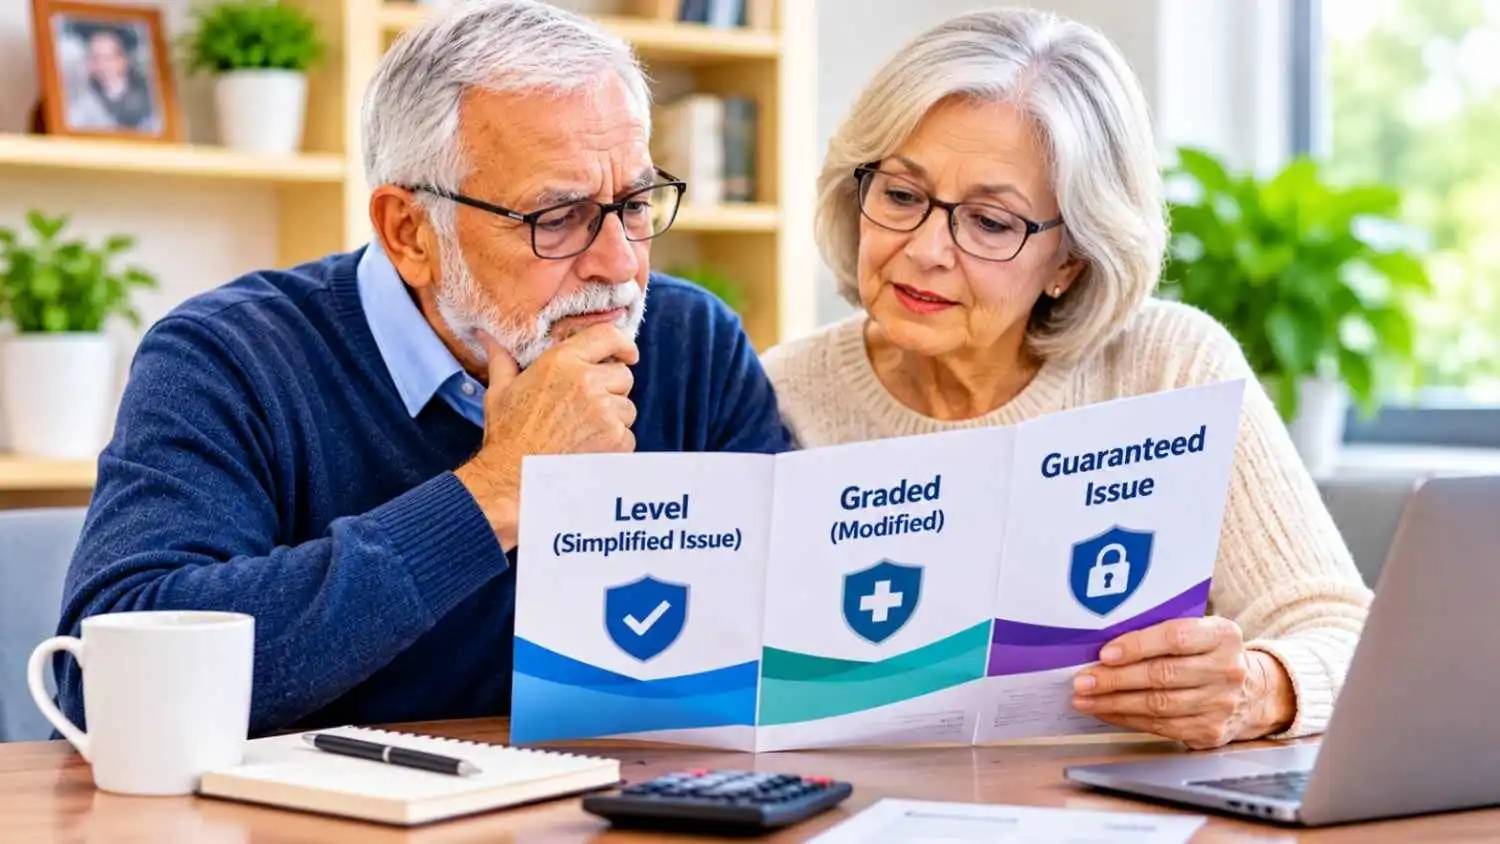
Your health history decides which of three versions you’re offered:
| Version | Health questions | Natural-cause death in first 2 years | Relative price | Typical fit |
| Level (simplified issue) | 8–15 yes/no | Full benefit | Lowest | Controlled, stable conditions |
| Graded or modified | Short questionnaire | Partial benefit, or premiums plus interest | Middle | Conditions just outside level cutoffs |
| Guaranteed issue | None | Premiums plus about 10% interest | Highest | Declined elsewhere, or serious illness |
The insurer makes that call from your answers and database checks, so two companies can place the same person in different rows.
Burial Insurance No Medical Exam Doesn’t Mean No Health Questions
No exam means no nurse visit, blood draw or urine sample. It doesn’t mean nobody checks. Simplified issue applications typically ask 8 to 15 yes/no questions, and insurers also pull prescription history and the MIB database that life insurers share. A medication on that record can contradict an answer you gave, which is where many surprises come from.
Certain questions sink applications at most carriers: current hospice care, living in a nursing facility, being bedridden, a terminal diagnosis, dialysis, an organ transplant, metastatic cancer and prescribed oxygen. Blood pressure and cholesterol rarely make the list.
Time windows matter more than people expect. “In the last two years” and “have you ever” are different questions, so someone 26 months past a stroke could pass at one company and fail at another that looks back five years.
Answer every question accurately. A claim can be denied if the application misstated a health fact, and insurers examine that most closely during the contestability period, commonly the first two years. Ask for a copy of what you signed.
Burial Insurance for Seniors with Health Problems: Which Conditions Matter Most
Insurers don’t judge a diagnosis by its name alone. They look at how recently it happened, how well it’s controlled, and whether you have more than one. That’s why burial insurance with pre-existing conditions works as a sorting exercise rather than a pass/fail test. Most final expense insurance for seniors gets sorted into the level, graded and guaranteed tiers described above, so the same condition can land in a different tier at a different company. The table below shows broad patterns, not promises (general information, with insurer-specific exceptions).
| Condition | Often workable at level or graded tiers | Often points to guaranteed issue |
| High blood pressure or cholesterol | Usually accepted on medication | Rarely the deciding factor |
| Type 2 diabetes | Managed with oral medication, no complications | Insulin use together with complications such as neuropathy or kidney disease, at some insurers |
| Cancer history | Treatment ended two to five years ago (window varies by insurer) | Active treatment, metastatic disease or recurrence |
| Heart attack or stroke | A single event, 12 to 24 months ago or more | A recent event, or more than one |
| COPD | Stable, no oxygen | Oxygen prescribed |
| Dialysis, organ transplant or dementia | Rarely | Typically |
Your medication list can weigh as much as the diagnosis itself. And one table can’t capture every quirk: burial insurance with diabetes, burial insurance with COPD and burial insurance after a heart attack or stroke each come with their own underwriting rules.
Simplified Issue Burial Insurance vs. Guaranteed Acceptance Burial Insurance
Simplified issue burial insurance is the place to start because it’s the cheapest route to a full benefit on day one. If your conditions are controlled and recent events fall outside the lookback windows, you may pass. A decline at one company doesn’t close the door elsewhere, and some insurers sell graded products aimed at people just outside the standard cutoffs.
Guaranteed acceptance burial insurance is the backstop. Since the insurer can’t turn you away, it protects itself with price and time. Industry sources commonly put guaranteed premiums roughly 30% to 60% above simplified issues for the same amount (estimate), and the benefit is limited during the waiting period.
Eligibility is narrower, too. Guaranteed issue final expense insurance typically starts at 45 or 50 and stops at 80 or 85, with face amounts around $25,000 or less. State rules add wrinkles: one national carrier’s guaranteed product sells only to ages 50 through 75 in New York, and another isn’t offered in Montana.
If you can pass simplified underwriting, take that route. A policy that can’t decline you isn’t better for that reason alone.
Burial Insurance Waiting Period: What Families Actually Receive
The waiting period is the biggest trade-off in burial insurance with pre-existing conditions. On guaranteed policies, a natural-cause death inside the window returns the premiums paid plus interest, often 10%. Accidents are treated differently: most policies pay the full face amount from the first day.
For example, a $15,000 guaranteed policy costs $60 a month, and the policyholder dies of an illness after 14 months. Premiums paid come to $840, so the family receives about $924. After month 24, the same policy pays the full $15,000.
Graded plans built on simplified underwriting work in steps instead, paying something like 30% of the face amount in year one and 70% in year two before reaching 100%. Schedules vary, so ask for the exact table in writing. Policies also tend to limit suicide benefits for the first two years, and some states set that period at one year.
If you want a policy that pays in full from day one, expect to answer health questions first, because burial insurance with no waiting period is built on passing underwriting rather than on guaranteed acceptance.
If a waiting period applies to you, set aside a small funeral fund or tell a relative about the gap, so the family isn’t surprised.
Burial Insurance Cost with Health Conditions: Funeral Prices and Sample Premiums
Start with what the policy has to cover. These are national medians from the NFDA’s 2023 General Price List Study, the most recent complete dataset we could confirm:
| Item | National median (NFDA, 2023) |
| Funeral with viewing and burial | $8,300 |
| Funeral with viewing and cremation | $6,280 |
| Basic services fee | $2,459 (burial), $2,495 (cremation) |
| Metal casket | $2,500 |
| Burial vault | $1,695 |
| Embalming | $845 |
Half of funeral homes charge more than these medians. Cemetery plots, opening and closing fees and headstones are usually billed separately and can add thousands. Burial costs rose 5.8% between 2021 and 2023, and local prices swing widely; cremation costs in Georgia, for instance, start near $900 for the most basic arrangement.
Now the premiums. These are sample monthly rates for a non-tobacco applicant on a simplified issue whole life policy, taken from Choice Mutual’s quote calculator (March 2026):
| Age | Female, $10,000 | Male, $10,000 | Female, $25,000 | Male, $25,000 |
| 50 | $24 | $31 | $55 | $71 |
| 60 | $33 | $43 | $76 | $103 |
| 65 | $41 | $54 | $97 | $130 |
| 70 | $53 | $70 | $127 | $169 |
| 75 | $71 | $97 | $172 | $238 |
| 80 | $98 | $135 | $241 | $332 |
Estimate: your quote depends on the insurer, your state, tobacco use and your health tier. Applicants placed in graded or guaranteed tiers pay more than these figures, and tobacco users generally pay substantially more. Coverage scales predictably; $25,000 costs roughly 2.3 to 2.5 times the $10,000 price at each age.
A reality check on total burial insurance cost: a 70-year-old man paying $70 a month spends $8,400 over ten years for a $10,000 benefit. The policy pays out more than he put in only if he dies before about the twelve-year mark. What he’s really buying is certainty that cash exists.
Step-by-Step: How to Get Burial Insurance with Pre-Existing Conditions
1. Write down your health history – List diagnoses, dates, medications, hospital stays and the date of your last treatment. Applications are date-driven, so this speeds up answers and cuts mistakes.
2. Price the funeral you want – The FTC’s Funeral Rule requires funeral homes to quote prices by phone and give an itemized price list in person. Pick a face amount that covers that figure plus cemetery costs, not a round number that merely sounds safe.
3. Quote several insurers, simplified issue first – Questions and lookbacks differ, so one decline isn’t a verdict. Comparing the top burial insurance companies is a reasonable way to build a shortlist, but no ranking can tell you who will accept your particular conditions. For that, you have to ask each insurer directly.
4. Answer truthfully, then read the application back – A mismatch with your prescription record is a common reason applications stall or claims get questioned.
5. If you’re declined, ask which question triggered it – Then try an insurer with a shorter lookback, a graded plan, and finally guaranteed acceptance.
6. Read the benefit schedule before paying – Check the waiting period, graded percentages, suicide clause and state availability. Most states also provide a free-look window, commonly 10 to 30 days, to cancel for a refund.
7. Tell your beneficiary – Share the insurer’s name and policy number, since a policy nobody knows about pays nothing.
Final Expense Insurance with Pre-Existing Conditions After 70
Waiting costs you twice. Premiums climb with every birthday, and a 70-year-old’s rate in the table above runs about double a 50-year-old’s. Health tends to get more complicated too, which can push someone from a level plan into a graded or guaranteed one. Applying for burial insurance with pre-existing conditions at 58 will almost always cost less than applying at 72 with more diagnoses. If you’re already past that age, the options for final expense insurance for seniors over 70 are narrower, so compare carefully before settling on a plan.
Alternatives When a Policy Doesn’t Fit
Insurance isn’t the only way to cover a funeral, and sometimes it isn’t the cheapest.
- Preneed contract: locks in prices with one funeral home. Ask whether it’s refundable, whether it transfers if you move, and how the money is protected under your state’s rules.
- Payable-on-death bank account: you stay in control, the money is available quickly, and it generally passes to the named person outside probate (rules vary by state).
- Group life through an employer: check whether the coverage can be converted to an individual policy after you leave.
- Simpler arrangements: direct cremation or direct burial skips the viewing and embalming, which alone carried an $845 median charge in 2023.
For burial insurance with pre-existing conditions, a smaller policy plus a savings cushion is sometimes cheaper than the largest policy you can qualify for. Pairing a modest burial insurance benefit with a payable-on-death account also keeps cash within reach if a waiting period hasn’t ended yet.
Warning Signs Before You Buy a Burial Insurance Policy
Burial insurance with pre-existing conditions attracts a lot of sales pressure, and the pitch doesn’t always match the contract. Slow down if you see any of these:
- An ad promising guaranteed acceptance and full coverage from day one for every cause of death
- No written benefit schedule before you pay
- Pressure to buy a bigger face amount than your funeral costs justify
- A suggestion to leave a health condition off the application to keep the price down
- A mailer or call that makes it hard to tell which insurance company actually issues the policy
- A push to replace an existing policy, since a new one generally restarts both the waiting period and the contestability clock
FAQs
Can burial insurance companies deny me?
On simplified issues and graded policies, yes. A knockout answer or a conflicting prescription record can lead to a decline. Guaranteed acceptance policies can’t turn you down for health, though age, residency and state availability still apply.
How much does burial insurance cost per month?
For $10,000 of non-tobacco simplified issue coverage, sample rates run from about $24 (a 50-year-old woman) to $135 (an 80-year-old man). Graded and guaranteed tiers typically cost more. Only a quote shows your price.
Can you get burial insurance with pre-existing conditions?
Yes. Simplified issue policies accept many controlled conditions, graded policies catch some applicants who miss those cutoffs, and guaranteed acceptance policies take people in their age range without health questions. What varies is the price, the benefit timing and which insurers will say yes.
Does the beneficiary have to spend the money on the funeral?
No. Burial insurance pays a cash benefit to the named beneficiary, who can use it for the funeral, cemetery costs, debts or anything else. Some people assign the benefit to a funeral home, but that is a separate choice.
Before You Apply
Nobody enjoys shopping for a policy that pays out after they’re gone, and it’s easy to rush when the calls and mailers start arriving. Slow down, get the benefit schedule in writing, and compare at least three insurers. Your state insurance department can verify an agent’s license if something feels wrong. At Insurance Centrik, the goal is to provide clear information, not a sale policy, so use the numbers above as a starting point and check them against a real quote.

Aarvith is the author and founder of Insurance Centrik. He researches various insurance topics, including auto, health, travel, home, and business insurance. He provides accurate insurance information from reliable sources and industry expertise.