Burial insurance, also called final expense insurance, is a small whole life policy, usually $5,000 to $25,000, made to help pay funeral costs. It is often easy to qualify for. Life insurance is the bigger category. It can pay much more to replace income, cover debts, or protect a mortgage. Burial insurance is a type of life insurance.
Burial Insurance vs Life Insurance: Key Differences Compared
| Feature | Burial insurance (final expense) | Life insurance (term or permanent) |
| Main purpose | Help pay funeral and end-of-life costs | Protect your family’s long-term finances |
| Typical coverage | Often $5,000 to $25,000 (some carriers go higher) | From small amounts to hundreds of thousands or millions |
| Policy type | Whole life: lasts your lifetime, fixed premiums | Term (ends after a set number of years) or permanent |
| Health requirements | No exam. Some policies ask a few health questions, and some ask none | May need a medical exam and full underwriting |
| Waiting period | Guaranteed issue policies usually have 2 to 3 years | Fully underwritten policies usually have none |
| Typical ages | Often 50 to 85 (varies by company) | Term options get harder to find as you age |
| How the money is used | Beneficiary can spend it freely | Beneficiary can spend it freely |
Note – Coverage amounts, ages and waiting periods differ by company and state. Always read the policy before you buy.
Is burial insurance the same as life insurance?
Almost. Burial insurance is one kind of life insurance. Think of “life insurance” as the whole family of products, and burial insurance as one small, focused member of that family.
One point surprises many people: burial insurance does not have to be spent on the funeral. The company pays the death benefit as cash to your beneficiary. Your beneficiary can pay the funeral home, a medical bill, or anything else. The name describes what the policy is built for, not a rule about how the money must be used.
This is different from a pre-need funeral plan, which is a contract with a specific funeral home to provide specific services.
What is burial insurance?
Burial insurance is a smaller whole life policy. It pays a set amount to your beneficiary when you die. Because it is your whole life, the policy is meant to last your whole life as long as you keep paying, and the premium stays fixed.
There are two common types:
- Simplified issue. You answer a few health questions. There is no medical exam. If you qualify, the full benefit may start right away, though some policies still use a waiting period.
- Guaranteed issue. There are no health questions. Guaranteed Issue Life Insurance can be an option if you meet the age requirements but have been turned down for other coverage. The tradeoff is a waiting period and, usually, a higher cost for the same amount of coverage.
Burial insurance is most often bought by people over 50, but there is no rule that says only seniors can have it.
How burial insurance works, step by step
- Choose a type – Decide between simplified issue and guaranteed issue. If you are in fair health, ask for simplified issue first.
- Apply –The application is short. There is no medical exam.
- Pay your premium – You pay monthly or yearly. The amount is set when the policy starts. If you stop paying, the policy can lapse, so ask about the grace period.
- Wait out any waiting period – Some policies pay the full benefit right away. Guaranteed issue policies usually do not (see below).
- Your beneficiary files a claim – They send the insurer a copy of the death certificate and a claim form. Payment time depends on the company and the paperwork. Smaller policies are often simpler to process, but no company can promise an exact day.
The waiting period, explained
This is the most important detail on a guaranteed issue policy.
During the first 2 to 3 years (the “graded” or “waiting” period), if the insured person dies from natural causes, most policies pay back the premiums paid plus interest, often about 10%. They do not pay the full face amount. After the waiting period ends, the full benefit is paid. Accidental death is commonly paid in full from day one, but check each policy.
Simple example (an illustration, not a quote): Say someone paid $1,200 in total premiums in the first year and died of an illness. A policy that pays premiums plus 10% would pay $1,320, even if the policy’s face amount was $10,000.
This is why you should ask every agent: “Is there a waiting period, and what exactly is paid if I die during it?”
How much does a funeral cost in the U.S.?
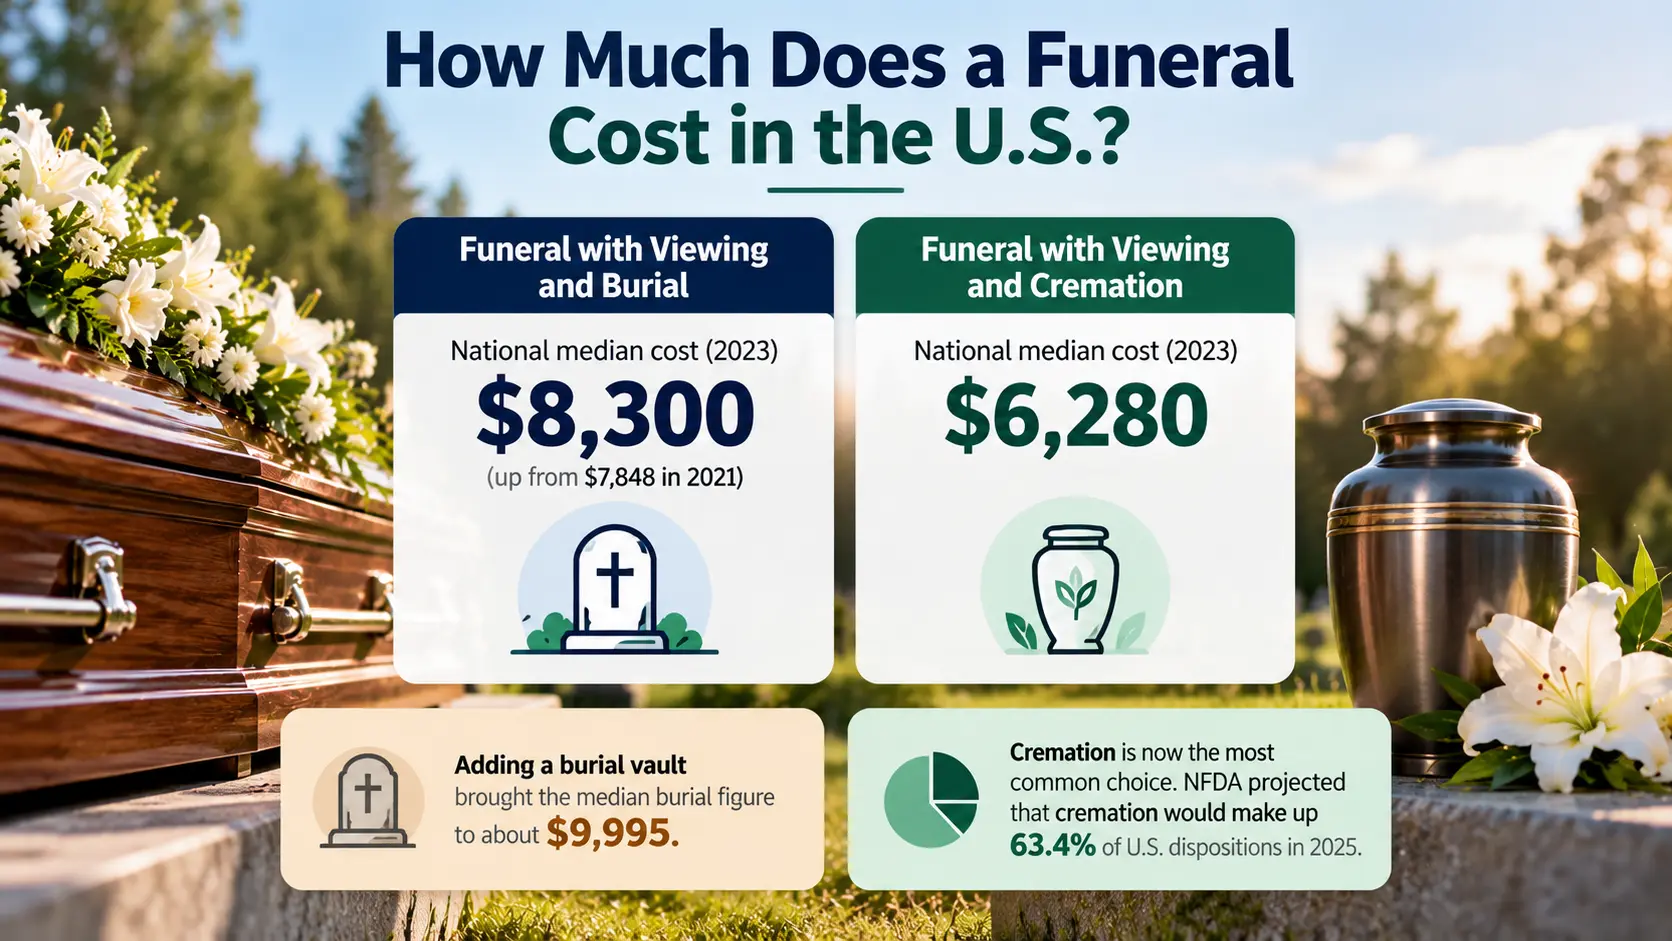
The National Funeral Directors Association (NFDA) tracks funeral prices. In its 2023 General Price List Study:
- A funeral with viewing and burial had a national median cost of $8,300, up from $7,848 in 2021.
- A funeral with viewing and cremation had a median cost of $6,280.
- Those medians do not include cemetery costs such as the plot, grave opening and closing, or a marker. Adding a burial vault brought the median burial figure to about $9,995.
Prices vary a lot by state, city and funeral home. These are national medians, not what your family will pay. Cremation is also now the most common choice. NFDA projected that cremation would make up 63.4% of U.S. dispositions in 2025.
This is why many families ask how much coverage is “enough.” A $10,000 policy may cover a typical funeral, but not always. A $5,000 policy may cover only part of the bill.
What is life insurance?
Life insurance pays a lump sum to your beneficiaries when you die. It comes in a few main forms:
- Term life covers you for a set number of years, such as 10, 20 or 30. It usually costs less per dollar of coverage, but it ends when the term ends.
- Whole life lasts your lifetime and builds cash value over time. Whole Life Insurance Rates for Seniors can vary based on age, health, coverage amount, and the insurer.
- Universal life is a flexible permanent policy that also builds cash value.
In the U.S., life insurance death benefits paid to a beneficiary are generally not subject to federal income tax. Tax rules can differ in some situations, so ask a tax professional about your case.
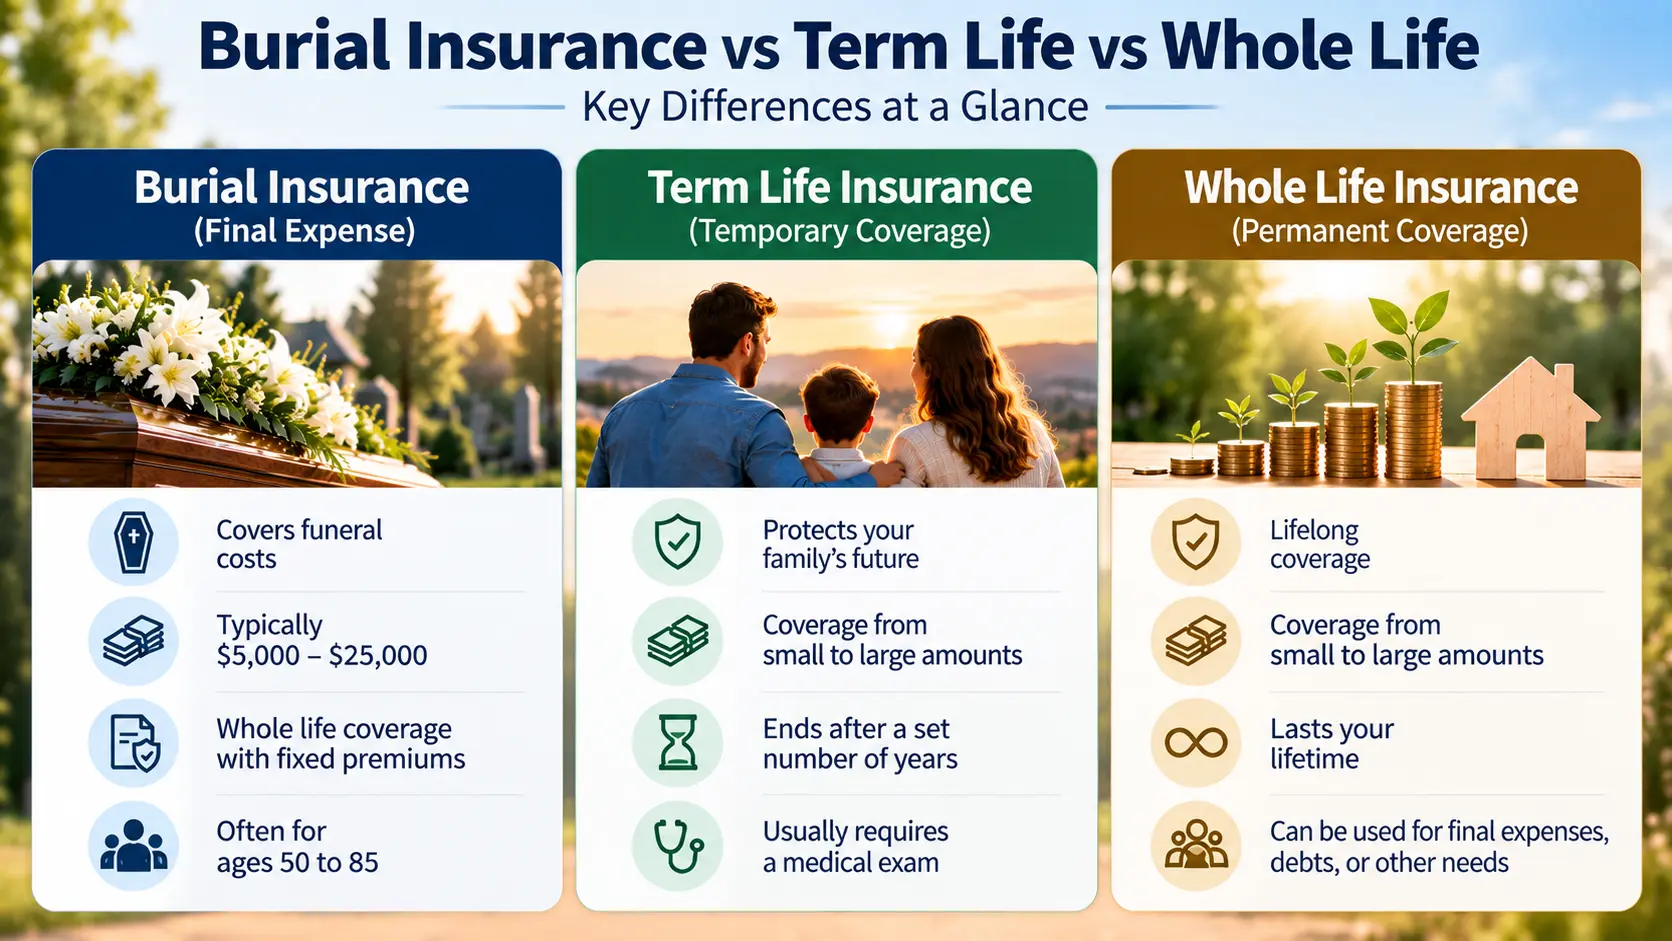
Burial insurance vs term life vs whole life
| Feature | Burial insurance | Term life | Whole life |
| How long it lasts | Your lifetime, if premiums are paid | A set number of years | Your lifetime, if premiums are paid |
| Coverage size | Small | Can be large | Can be large |
| Cost per dollar of coverage | Often higher than term | Usually lower | Usually higher than term |
| Health checks | Few or none | Often an exam or detailed health review | Often an exam or detailed health review |
| Builds cash value | Typically small if any; check the policy | No | Yes |
Term life often gives the most coverage for the least money, but only if you can qualify and only for a set period. That is why the right choice depends on your age, health and goals.
Is Burial Insurance or Life Insurance Better?
Neither burial insurance nor traditional life insurance is automatically better. The right choice depends on what you want the policy to do, how much coverage you need, your age and health, and how much you can comfortably pay.
Burial insurance – When your main goal is to leave money for funeral costs and other final expenses. It can also be worth considering if you are older or have health conditions that make it difficult to qualify for a traditional life insurance policy. Because coverage amounts are usually smaller, burial insurance is generally designed for final expenses rather than long-term income replacement.
Traditional life – When someone depends on your income or you need a larger death benefit. For example, a parent with young children, a mortgage and several years of income to protect may need much more coverage than a typical burial insurance policy provides.
A simple way to think about it is:
| Your main need | Option to consider |
| Help with funeral and final expenses | Burial insurance |
| Replace income for your family | Life insurance |
| Protect a mortgage or large debts | Life insurance |
| Need a relatively small amount of coverage | Burial insurance |
| Need hundreds of thousands of dollars in coverage | Traditional life insurance |
| Health makes other coverage difficult to qualify for | Guaranteed issue burial insurance may be worth comparing |
Before choosing, compare the actual policy terms rather than relying only on the product name. Coverage amounts, premiums, health requirements and waiting periods can vary by insurer and state.
Is Burial Insurance Cheaper Than Life Insurance?
Burial insurance can have a lower monthly premium than a large traditional life insurance policy simply because you are buying a much smaller death benefit. That does not necessarily mean it is cheaper for the amount of coverage you receive.
For example, someone might compare a small burial policy intended primarily for final expenses with a much larger term life policy designed to replace income. Looking only at the monthly premium would not be a fair comparison because the two policies provide very different amounts of coverage.
Term life insurance generally offers larger coverage amounts for a set period and can provide more coverage per premium dollar for people who qualify. Burial insurance, especially guaranteed issue coverage, may cost more relative to its smaller death benefit because the insurer accepts applicants with limited or no health underwriting.
Your actual premium can depend on factors such as:
- Age
- Health and medical history
- Tobacco use
- Coverage amount
- Type of policy
- Insurer
- State of residence
If you can qualify for both, compare the premium, death benefit, length of coverage and waiting period rather than choosing whichever policy has the lowest monthly payment.
Three example situations
These are simple illustrations, not advice. Your own situation may be different.
- A 35-year-old parent with a mortgage – The family’s biggest risk is lost income. Term life is often the first thing to look at, because it can offer large coverage at a lower cost per dollar.
- A 72-year-old with a serious heart condition and little savings – Other coverage may be hard to get. A guaranteed issue burial policy can help, but the waiting period matters and the price may be higher per dollar of coverage. Final Expense Insurance for Seniors Over 70 may be another option to consider when health or age makes it harder to qualify for other coverage.
- A 58-year-old in good health with a paid-off home – Funeral costs are the main worry. A simplified issue policy may offer more coverage for less than guaranteed issue, so compare both.
Common mistakes to avoid
Thinking burial insurance is cheaper –The monthly bill is usually lower because the coverage is smaller. Per dollar of coverage, it can cost more than term life. Compare quotes for both.
Skipping the waiting period – Read what is paid if death happens in the first 2 to 3 years
Assuming guaranteed issue is best for everyone – If you are in fair health, a simplified issue policy may give you more coverage for less money. Guaranteed issue is built for people who cannot qualify elsewhere.
Buying more or less than you need – Add up funeral costs, debts and what your family would need to live on. Then choose coverage to match.
Forgetting to name and update your beneficiary – The money goes to whoever is listed on the policy.
Not telling your family – A policy is useless if no one knows it exists. Tell your beneficiary where the paperwork is.
Questions to ask before you buy
- Is this simplified issue or guaranteed issue?
- Is there a waiting period? What is paid if I die during it?
- Will my premium stay the same for life?
- What happens if I miss a payment?
- Is the company and the agent licensed in my state? (Your state department of insurance can confirm.)
- How is the company rated for financial strength?
Choosing the Right Insurance for Your Family
Choosing between burial insurance and life insurance comes down to what your family may need after you’re gone. If you mainly want help covering funeral and final expenses, burial insurance may make sense. If your family would also need help with a mortgage, bills, debts, or lost income, a larger life insurance policy may be a better fit.
Think about your budget, how much coverage your family would actually need, and how long you want the coverage to last. Insurance Centrik can help you learn more about burial insurance coverage and the things worth comparing before you choose. Your age and health can also affect which policies are available to you.
Don’t choose a policy based on the monthly price alone. Look at the coverage amount, premium, waiting period, and policy terms together. If you’re unsure about any part of a policy, a licensed insurance agent in your state can explain the details before you make a decision.
FAQs
Do I need a medical exam for burial insurance?
Usually no. Simplified issue asks a few health questions. Guaranteed issue asks none.
Can I have both burial insurance and life insurance?
Yes. Some people use life insurance to protect their family's income and a small burial policy for final costs.
What does a funeral cost in the U.S.?
According to NFDA's 2023 study, the national median is $8,300 for a funeral with viewing and burial and $6,280 for a funeral with viewing and cremation. Cemetery costs are extra, and prices vary by location.
How much coverage does burial insurance usually offer?
Most policies fall between $5,000 and $25,000, though some companies offer more. Coverage amounts and ages vary by company and state.

Aarvith is the author and founder of Insurance Centrik. He researches various insurance topics, including auto, health, travel, home, and business insurance. He provides accurate insurance information from reliable sources and industry expertise.